Does Home Insurance Cover a Broken Well Pump? The Straight Answer
Your well pump quits. You need to know if your insurance will pay for it, fast.
We will cover what home insurance typically covers, what it almost always excludes, and how to handle a claim.
I’ve been on both sides of this as a technician and homeowner. Here’s the truth: dig out your policy document right now and read it.
The Short Answer: When Your Policy Will and Won’t Pay
Home insurance follows one basic rule. It pays for sudden, accidental damage from a specific event your policy lists as a “covered peril.” It does not pay for something that breaks down from age, wear and tear, or a lack of maintenance.
Think of it like your car insurance. If a tree falls on your parked car, that’s a covered accident. If your car’s engine seizes because you never changed the oil, that’s a maintenance failure. Insurance won’t cover the engine. The same logic applies to your well pump.
A pump that grinds to a halt after 15 years of service is a maintenance issue, plain and simple, and filing a claim for it will get denied. You’re responsible for replacing worn-out equipment. Insurance exists for the unexpected disasters.
This is the core concept you must understand: “sudden and accidental” versus “gradual deterioration.” If damage happens in an instant from an outside force, you might have a claim. If it happens slowly over years, you definitely do not.
What Kind of Well Pump Damage Might Be Covered?
Coverage depends on what caused the damage. Here are specific “covered perils” that could realistically destroy a pump:
- Lightning strike or a severe power surge from a storm.
- A tree or large branch falling and crushing an above-ground pump house.
- A vehicle hitting and damaging your well cap or piping.
- Vandalism or theft of the pump or control equipment.
If a covered event destroys your pump and water floods your basement, the water damage to your home is often covered under the “dwelling” or “personal property” part of your policy, even if the pump itself isn’t. This is a key distinction. Always report major water damage immediately, especially in cases like basement flooding due to storm pump failure.
For most policies, your well pump is considered part of the home’s plumbing system. It’s attached to the structure and essential for operation. This means the pump itself is typically covered under “Dwelling Coverage” (Coverage A) if a named peril hits it, not under a separate category.
Location affects risk. An above-ground jet pump in a shed is exposed to falling objects or vehicle impact. A submersible pump deep in the well is protected from those things but is still vulnerable to lightning surges or vandalism at the control box. Always check where your specific perils are listed.
Water Science Snippet: A lightning strike near your property can induce a massive voltage surge through your power lines and grounding system. This surge can travel into your pump’s control box and motor, frying the electronics in milliseconds. That’s the textbook definition of “sudden and accidental” damage insurers look for.
The Big Exclusions: What Insurance Almost Never Covers
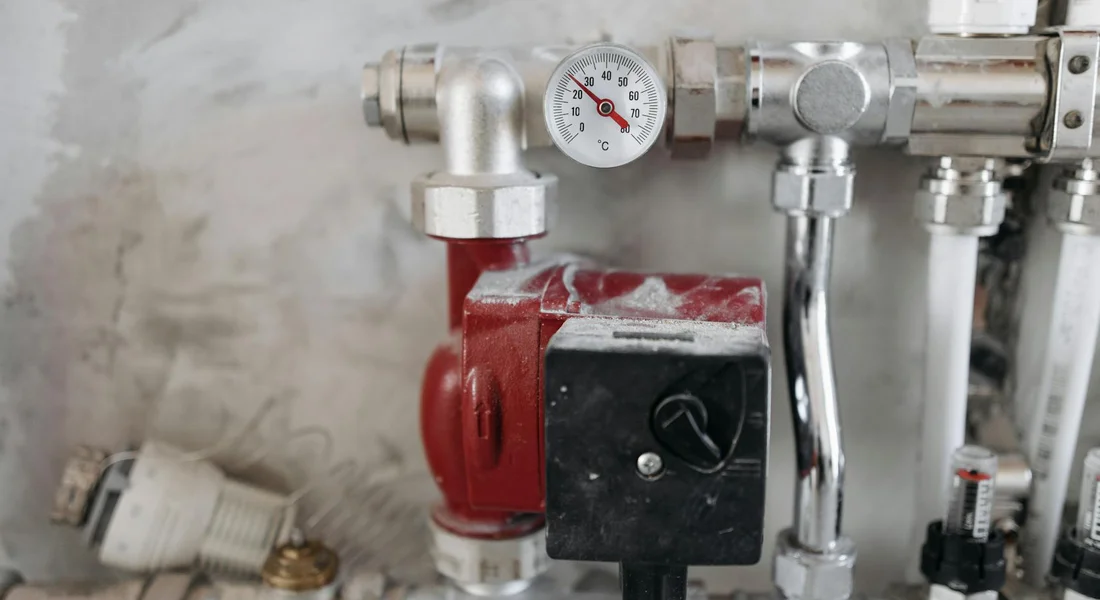
Your homeowner’s insurance is for sudden, accidental disasters. It is not a maintenance plan. The single biggest reason a well pump claim gets denied is failure classified as normal wear and tear. Regular well pump inspections and valve maintenance can help prevent wear from being misclassified as normal wear and tear. That’s why routine well pump inspection and valve checks are essential parts of a preventive maintenance approach.
Insurance policies explicitly exclude breakdowns from rust, corrosion, sediment buildup, or just plain old age. A pump that finally quits after 15 years of service is not an insured event. It’s an expected maintenance cost, like replacing a worn-out water heater.
A well running dry is also not covered. Your policy covers damage to your home and structures, not the guaranteed presence of a natural resource. If your water table drops and the well goes dry, that’s a resource issue you must solve, not an insurance claim.
Damage from floods or earthquakes needs its own policy. A standard homeowner’s policy won’t touch it. If floodwaters ruin your pump, you need separate flood insurance. The same goes for earthquake damage.
Contamination is a gray area. If a pump failure somehow leads to bacteria or sediment contaminating your water supply, it becomes a complex liability and health issue. This is rarely a straightforward property damage claim under your standard policy.
The “Red Flag” Troubleshooting Guide
These are classic signs of normal wear. If you report these to your insurer, they will likely point to the wear and tear exclusion.
- Short Cycling: The pump turns on and off constantly, every few minutes. This usually means a bad pressure switch or a waterlogged pressure tank, both common wear items.
- The Slow Fade: Your water pressure has been dropping steadily over months. This points to a pump wearing out or scale buildup in pipes.
- The Growing Groan: Strange noises (grinding, screeching) that started quietly and got louder over time indicate bearing or impeller wear.
If your pump was working fine yesterday and is completely dead today with no visible cause, that’s more likely a sudden failure you should call your insurer about, especially if you missed any warning signs of sump pump failure.
What About Warranties and Home Warranties?
Do not confuse insurance with a warranty. They are completely different.
A manufacturer’s warranty covers defects in materials or workmanship for a set period. For example, a Red Jacket submersible pump often comes with a lifetime warranty for the original homeowner, but it only applies if the pump fails due to a manufacturing flaw, not normal use. You’ll still pay for the labor to pull it and reinstall it.
A home warranty is a service contract you buy separately. It might cover well pump repair or replacement. The keyword is “might.” Home warranties for well pumps come with strict dollar caps, high service fees per call, and lists of pre-existing conditions they won’t touch. They are not insurance. They are a repair service with fine print.
How to File a Well Pump Claim: A Step-by-Step Guide
Difficulty Rating: Claim Process (Difficulty 3/10). The steps are simple. The paperwork requires attention.
- Stop and Mitigate. Turn off the pump’s power at the breaker. Do not keep trying to run it. If there’s water damage from a burst pipe related to the failure, try to stop the flow and move belongings. This is your duty under the policy.
- Call Your Insurer. Do this immediately. Report the failure and any damage. They will open a claim file and assign an adjuster. Be clear about what happened and when.
- Get a Professional Diagnosis. Hire a licensed well contractor. You need a written, itemized report stating the cause of failure. If the contractor says “lightning strike” or “power surge,” that’s a strong case. If they say “worn out bearings,” your claim is probably dead.
- Document Everything. This is what makes or breaks your claim.
Your documentation package must include:
- The contractor’s detailed repair quote with the diagnosed cause of failure.
- Clear photos and video of the damaged pump, any related water damage, and the overall well setup.
- Any proof of the pump’s condition before it failed. A recent service receipt is gold.
Remember your deductible and coverage limits. If your pump replacement costs $2,000 and your deductible is $1,500, filing a claim for $500 is not worth it. It will also count as a claim on your record, which can raise your rates.
What Helped Me: I keep a folder in my basement with my pump’s model and serial number, the installation receipt, and every service record. When my neighbor had a claim, he spent days digging for his info. My paperwork was ready in two minutes. It speeds everything up.
Understanding the Real Costs: Insurance, Taxes, and Out-of-Pocket
Standard homeowner’s insurance is for sudden, accidental damage. It is not a maintenance warranty. A pump that quits from old age or normal wear won’t be covered. Your insurance company views a worn-out well pump the same way it views worn-out brakes on your car; it’s your responsibility to maintain it. Some homeowners add water/sewer line insurance to cover failures beyond maintenance. Whether it’s worth it depends on your home’s age and the potential repair costs.
How to Increase Your Coverage
You can sometimes buy extra coverage. Ask your agent about an “equipment breakdown” endorsement or a “service line” endorsement. These can cover mechanical failure of home systems, including well pumps, that your main policy excludes. There is an extra premium, and it still has a deductible, but it can be a smart buy for peace of mind.
Can I Write a Well Pump Off on My Taxes?
For your primary home, almost never. The IRS sees this as a personal expense, like fixing a dishwasher. If the well pump is for a rental property you own, it may be deductible as a repair expense or depreciated over its lifespan. If you have a legitimate home office with specific IRS qualifications, a portion might be deductible. This is a firm “talk to your tax professional” situation. Do not guess.
Out-of-Pocket Costs: Repair vs. Replace
Set your expectations now. A simple repair, like replacing a pressure switch or a capacitor, might run $150 to $500. Repairing or rebuilding a submersible well pump is a bit more involved. For a standard submersible pump, installed, you’re looking at $900 to $2,500. The final cost depends on depth, pump horsepower, and local labor rates. A deep well or a complex jet pump system can push that higher.
Landlord Policy vs. Homeowner Policy
If you own a rental property with a well, you need a landlord (dwelling fire) policy, not a standard homeowner’s policy. The structure is covered, but appliances and systems often are not. As the landlord, you are responsible for providing working water; you must budget for pump repairs as a cost of doing business. You might add equipment breakdown coverage to this policy as well.
Tools & Material Checklist (The Info You Need)
When your pump fails, you need information, not wrenches. Have this ready for your technician to get a fast, accurate quote:
- Pump model and horsepower (find this on the old control box or your purchase records).
- Well depth and casing diameter (on your well’s original “log” sheet).
- Pressure tank specifications (gallons, and if it’s a “bladder” or “captive air” tank).
- The phone number of a trusted, licensed well driller or pump installer.
Your Best Defense: Preventing Pump Problems and Claims
Forget the insurance paperwork for a minute. The cheapest repair is the one you prevent with basic, routine maintenance. This will always cost less than your deductible and avoids the hassle of a claim altogether.
System Maintenance Roadmap
Follow this simple annual schedule to catch small issues before they become catastrophic failures:
- Every 3 Months: Listen. Does the pump cycle on and off rapidly? Does it run for minutes when no water is being used? Unusual sounds or long run times are early warnings.
- Every 6 Months: Check the pressure tank’s air charge. With the pump off and water drained, use a tire gauge on the tank’s air valve. It should read 2 PSI below the pump’s “cut-on” pressure (e.g., 28 PSI for a 30/50 switch).
- Every Year: Test your water quality for basic parameters. A major shift in sediment or iron can indicate well or pump issues.
- Every 3-5 Years: Hire a professional for a full system inspection. They can check amp draw, line integrity, and tank condition.
Tips to Prevent Common Failures
These three actions significantly extend pump life:
- Install a Quality Surge Protector. Lightning and power grid surges are a top cause of pump motor failure. Protect the control box.
- Ensure Proper Pump Sizing. An oversized pump that constantly cycles on/off will wear out far faster than one correctly sized for your home’s demand.
- Maintain a Clean Well House. Keep the area around the pressure tank and equipment dry, clean, and free of rodents or insects that can chew wires.
The final verdict is this: for a well pump, your own dedicated maintenance savings account is the most reliable coverage you will ever have. Treat it like a required part of your home’s operating budget — especially when used in conjunction with regular maintenance.
Quick Answers
What If the Well Pump is Damaged by Flooding or Earthquakes?
Standard home insurance does not cover flood or earthquake damage. You need separate, specific policies for each of those perils. Treat this as a non-negotiable safety rule if you live in a risk area.
Does Insurance Cover Well Pump Replacement if the Well Runs Dry?
No. Home insurance covers damage to your home’s systems and structures, not the loss of a natural resource. A dry well is a groundwater issue, not an insurable event, and requires a hydrogeological solution.
What If the Well Pump Failure Causes Contamination or Water Quality Issues?
This becomes a serious health and liability issue, not a simple property claim. You must immediately stop using the water and get it tested. Coverage for remediation is complex and often requires specific endorsements, so call your insurer first.
What Should I Do *Right Now* if My Well Pump Fails?
First, turn off the pump’s power at the breaker to prevent motor damage. Then, check for any related water damage in your home and mitigate it. Your third call is to a licensed well professional for a diagnosis before you call your insurance company. If you’re unsure who to call for well pump service, start by researching licensed well pump contractors in your area. They can provide a diagnosis and guide you on the next steps.
How Can I Increase My Coverage for the Well Pump?
Ask your agent about an “Equipment Breakdown” endorsement. This can cover sudden mechanical failure from causes like power surges, which your main policy might limit. It’s an added premium but can be wise for essential, expensive equipment.
Your First Steps After a Well Pump Failure
Grab your home insurance policy and read it yourself to see what it says about well systems. If you need to file a claim, take clear pictures of the damage and get a detailed repair estimate from your technician first.
Written by Bob McArthur. Bob is a an HVAC and plumbing industry veteran. He has professionally helped homeowners resolve issues around water softeners, heaters and all things related to water systems and plumbing around their homes. His trusted advice has helped countless of his clients save time, money and effort in home water systems maintenance and he now here to help you and give you first hand actionable advice. In his spare time, Bob also reviews home water systems such as tankless heaters, water softeners etc and helps home owners make the best choice for their dwelling. He lives around the Detroit area and occasionally consults on residential and commercial projects. Feel free to reach out to him via the contact us form.